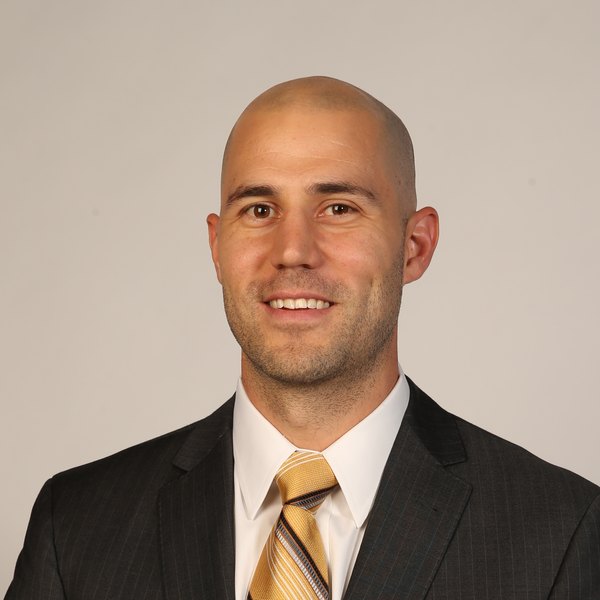
I am an Associate Professor and the Plumhoff Endowed Chair in Accounting at Baylor University's Hankamer School of Business. My research examines private equity and hedge funds, taxation, and financial reporting and disclosure — with particular attention to how regulation, monitoring, and reporting choices shape capital formation in private markets.
My work has appeared in The Accounting Review, Contemporary Accounting Research, the Journal of Corporate Finance, the Journal of Empirical Finance, the Journal of the American Taxation Association, and the Journal of Financial Reporting, among others. I have also submitted comment letters to the SEC on the regulation of private fund advisers.
Before entering academia I practiced as a CPA, serving as a Tax Manager at EKS&H and a Tax Associate at PricewaterhouseCoopers, specializing in natural resources, private equity, and partnership taxation. I hold a PhD in Management Science (Finance) from The University of Texas at Dallas and BBA and MS degrees from Texas A&M University. I remain a licensed CPA in Texas and Colorado.
Research Interests
Private Equity & Hedge Funds
Fund reporting quality, external monitoring, auditor choice, ESG disclosure, fundraising, and secondary market pricing.
Taxation
Investment income taxes, tax policy and asset prices, mark-to-market taxation, and tax compliance behavior.
Financial Reporting & Regulation
Voluntary reporting and audit choices by private firms, SEC oversight, disclosure, and misconduct.
Mergers & Acquisitions
Information about private targets, shareholder voting in the takeover market, and the pricing of tax risk in deals.
Recent Recognition
Contact
One Bear Place #98002
Waco, Texas 76798
Research
Working paper drafts are available on SSRN. A full CV is available for download.
Refereed Journal Publications
-
Textual Analysis of Private Equity Fund Mandatory SEC Filings: Evidence from ESG Disclosures and Fundraising OutcomesForthcoming
Abstract
We identify Environmental, Social, and Governance (ESG) disclosures in private equity (PE) advisers’ mandatory regulatory filings and examine the association between ESG disclosures and PE advisers’ ability to raise capital. We find environmental, but not social or governance, disclosures are, on average, negatively associated with fundraising, and that negative-toned or risk-related environmental disclosures drive this result. We also find that investors’ response to disclosure tone varies with their home location’s perceptions of ESG initiatives. Overall, our evidence suggests that (i) PE advisers’ environmental disclosures in regulatory filings contain decision-useful information, (ii) PE investors are uniformly averse to disclosed environmental risks, and (iii) PE investors’ responses to positively-toned environmental disclosures depend on their attitudes toward ESG. We provide insight into the implications of disclosure in the opaque PE setting, which informs potential regulatory efforts to increase both overall and ESG-specific disclosure by PE funds.
-
Private Equity Fund Reporting Quality, External Monitors, and Third-Party Service Providers
Abstract
We describe variation in the reporting quality (i.e., accuracy and bias of reported net asset values (NAVs)) of private equity (PE) funds across types of external monitors (investors and auditors) and third-party service providers (valuation specialists, marketers, and administrators). In contrast to public markets, we find only limited evidence that reporting quality varies with the composition and types of investors in PE funds. We observe, however, that reporting quality varies with auditor involvement and the use of third-party service providers; these associations often differ across buyout (BO) and venture capital (VC) funds and from those observed in public markets. Our evidence is important to investors and regulators, especially now that PE supersedes public markets as the main vehicle to raise capital and as regulators increase their focus on private markets. Data Availability: Data used in this study are available from public sources listed in the paper. JEL Classifications: G1; G14; G30; M4; M41.
-
Understanding Private Equity Funds: A Guide to Private Equity Research in Accounting
Abstract
Private equity (PE) funds are increasingly important to the economy and now serve as the primary vehicle for raising new capital. However, a limited understanding of the unique PE fund setting among accounting academics inhibits accounting research in this area. In this paper, we first describe the PE fund setting and explain how fundamental differences between PE and previously studied settings make it difficult to infer PE fund behavior from research performed using other settings. We then discuss how PE funds provide researchers with the ability to explore fundamental questions related to agency costs, governance, compensation, disclosure, and fair value accounting. Finally, we provide guidance on PE data sources available for use in future research. Because of the volume of economic activity currently funneled through PE and the unique aspects of the PE setting, it is important for researchers to explore when, why, and how accounting matters for PE funds. Data Availability: Data used in this study are available from the public sources identified in the text. JEL Classifications: G1; G14; G30; M4; M41.
-
A Note on Attributes Affecting Private Equity Fund Pricing in Secondary Markets
Abstract
Private equity (PE) funds are growing, beginning to take the lead in capital markets. In conjunction with this growth, secondary markets for PE fund ownership interests also have grown. Recent research investigates the valuation discount that sellers of PE fund interests incur in secondary markets, and suggests this discount is driven entirely by the illiquidity inherent in PE. This article describes how the legal structure of PE funds, instrumental to funds’ existence and operations but largely ignored in prior research, can impose a tax discount in addition to an illiquidity discount in the secondary market. Thus, it extends this new and important stream of research by highlighting that illiquidity may be only one attribute driving PE fund secondary market discounts and that after-tax, rather than pretax returns, warrant consideration in these markets. (c) 2023 PMR. All rights reserved.
-
The Importance of Target Information in the Acquisition of Privately Held Firms
Abstract
Privately held companies make-up the vast majority of targets in corporate takeovers. When disclosure is not required, acquiring firms usually provide little to no information about either the deal or the target in these transactions. The absence of such information may be innocuous if investors believe it to be unimportant. We examine whether investors respond to basic information disclosed by acquirers of private targets. Our evidence suggests investors respond to the disclosure of deal value whereas sales information of the target is unimportant compared to transactions where such information is not disclosed. Our results are robust to using a matched sample of deals with and without the disclosure of deal value and sales information. Using a subset of hand-collected data, our study also provides insight into the method and timing by which acquirers disclose information about private targets. Altogether, our evidence suggests regulatory policies surrounding seemingly insignificant, private acquisitions should consider the disclosure of deal value to be important to investors.
-
Investor Taxes and Option Prices
Abstract
We examine whether tax-sensitive investors play a significant role in options markets by examining whether option prices reflect investor taxes. Existing empirical option pricing literature ignores taxes. We exploit a unique setting where “index” options on the S&P 500 Index (SPX) and nearly identical “non-index” options on the exchange traded fund (ETF) tracking the S&P 500 Index (SPY) face different tax treatments. We find that higher investor taxes reduce option prices, indicating tax capitalization in options. We find consistent results when analyzing options around the investor tax changes enacted by the American Taxpayer Relief Act (ATRA) of 2012, and for options on stock indices other than the S&P 500 (e.g., Russell 2000). Altogether, our findings provide new evidence of an additional item—investor taxes—influencing option prices, suggesting that tax-sensitive investors play a non-trivial role in options markets and that taxes warrant consideration in broader options research. Data Availability: Data used in this study are available from public sources identified in the paper. JEL Classifications: H24; G12.
-
Does IRS Monitoring Deter Managers from Committing Accounting Fraud?
Abstract
We examine whether monitoring by the Internal Revenue Service (IRS) affects managers’ decisions to engage in fraudulent financial reporting. We argue that IRS monitoring provides a disciplining effect reducing managements’ incentives to engage in rent diversion activities such as costly financial statement misreporting. Using information on IRS audit rates and instances of fraud disclosed in Securities and Exchange Commission (SEC) Accounting and Auditing Enforcement Releases (AAERs), we find evidence consistent with IRS monitoring providing positive spillover effects in reducing the likelihood of accounting fraud. Our results are robust to using a matched sample of fraud and nonfraud firms. Altogether, we find evidence that tax authorities provide positive externalities in reducing agency costs through monitoring and enforcement.
-
The Effect of Industry Restructuring on Peer Firms
Abstract
We study the bond price reaction of a merged firms peers, in order to better understand how the market responds to a restructuring. We argue that a merger announcement may signal the possibility of a merger wave to the industry, and in doing so, increase the conditional probability that peer firms might themselves be acquired in the future. However, while peer firm equity holders expect a direct benefit from a potential acquisition—in the form of a price premium—peer firm bond holders can only expect an indirect benefit—in the form of a risk reduction. Consistent with these hypotheses, we show that price reactions are stronger for firms that have a higher unconditional probability of being acquired ex-ante. In addition, we document that, cross-sectionally, the abnormal returns we observe from peer bondholders are concentrated among firms that have the highest expected risk reduction benefit from a potential acquisition. In order to distinguish a potential reduction in risk as the explicit return driver, we show that abnormal bond returns within firm (between different bond issues) are also concentrated among issues that have the highest expected risk reduction benefit.
-
Investment Income Taxes and Private Equity Firms' Acquisition ActivityBest Paper
Abstract
Utilizing a novel identification strategy, we uncover evidence that investment income tax rate reductions increase acquisition activity of private equity acquirers. Applying a difference-in-difference methodology, we find that acquisitions sponsored by private equity firms nearly doubled following the Taxpayer Relief Act of 1997 and the Jobs and Growth Tax Relief Reconciliation Act of 2003. We attribute our findings to private equity firms' ability to capture the benefit of lower capital gains tax rates. These findings are robust to considering target shareholders' tax incentives as well as firm, industry, and macroeconomic factors possibly influencing acquisition activity.
-
Why Pay Our Fair Share of Taxes? How Perceived Influence Over Laws Affects Tax EvasionJATA Outstanding Manuscript
Abstract
We examine how the relation between taxpayers and their government affects tax evasion. Specifically, we examine how perceived influence over government policymaking affects firms’ decisions to evade tax. We argue that firms are less willing to comply with tax laws when they perceive the influence over their government to be unfavorable to them or the result of an unfair policymaking process. Consistent with this argument, we find that firms evade more tax when other domestic firms have more perceived influence over domestic government policymaking. This suggests a potential negative externality of lobbying: higher tax evasion by other firms. However, government effectiveness or lack of corruption eliminates the positive relation between evasion and perceived influence over policymaking. Our study is the first to document the relation between perceived influence over government policymaking and tax evasion, and our results suggest that limiting domestic firms’ influence over policymaking could help governments decrease tax evasion.
-
Does Shareholder Voting Matter? Evidence from the Takeover Market
Abstract
Voting rights are a basic shareholder-protection mechanism. Outside of the core voting requirements state law imposes (election of directors and votes on fundamental changes), federal law grants shareholders additional voting rights. But these rights introduce concomitant costs into corporate governance. Each grant of a voting right thus invites the question: is the benefit achieved worth the cost the vote imposes?
The question is not merely a theoretical one. Recently the SEC, concerned about Nasdaq’s potential weakening of shareholder voting protections, has lamented that little evidence exists on the value of the shareholder vote. This Article provides that evidence. It examines the implementation of a Nasdaq shareholder voting rule to identify the associated costs and benefits of requiring the approval of acquisitions by the acquiring firm’s shareholders. It finds firms alter the structure of their acquisitions to avoid shareholder voting. On its own, this finding could suggest self-serving behavior — managers may be avoiding shareholder votes to effectuate suboptimal transactions at the shareholders’ expense. Yet this Article finds no difference in returns to acquisitions that require a shareholder vote and those that do not. This lack of a difference suggests that, on average, for acquiring shareholders the costs outweigh the benefits associated with shareholder voting. Such results suggest that regulators and exchanges alike should be cautious when imposing shareholder voting requirements. The shareholder franchise, a relatively blunt and costly instrument, is best suited to fundamental corporate changes and director elections.
Working Papers
-
Misconduct and Fundraising in Private EquityR&R · Management Science
Abstract
As private equity (PE) funds’ economic importance increases, the debate intensifies on whether the industry requires more regulation. We study the effects of new disclosures required for PE fund advisers (i.e., general partners, or GPs). Specifically, we find that mandatory disclosure of misconduct generally reduces GPs’ ability to fundraise. Reputation concerns appear to lead both new and existing investors (i.e., limited partners, or LPs) to avoid misconduct GPs: public pension funds, large LPs, and LPs in Democratic states are most averse to GPs that disclose misconduct. We also find some evidence of LPs’ economic concerns: misconduct disclosure is related to GP crash risk. As regulators look to expand PE regulation, our study informs regulators of the various effects of mandatory disclosures on PE funds and the mechanisms underlying those effects.
-
Does Accounting Matter for Capital Formation? Determinants and Consequences of Private Equity Fund Financial Reporting ChoicesR&R · Contemporary Accounting Research
Abstract
Private equity (PE) funds are increasingly important to the economy and to investors, yet we know little about many aspects of these inherently opaque and lightly regulated funds. We study the fundamental financial reporting choices – audit, auditor, and accounting standard – of PE funds and evaluate whether these choices affect funds’ capital formation. We find that fund size and ownership characteristics are associated with decisions to obtain an audit, use a Big 4 auditor, and prepare GAAP financial statements. These results suggest that PE funds’ agency costs and investors’ information needs influence funds’ financial reporting choices. However, we find little evidence that financial reporting facilitates PE fundraising. Results are consistent with either financial reporting failing to aid capital formation in PE markets, in contrast to other markets, or with PE funds voluntarily choosing financial reporting only when needed (e.g., only used by funds that would have worse fundraising without reporting). In either case, results are inconsistent with recent SEC efforts to regulate PE fund financial reporting and suggest that mandates would impose requirements on funds that are unlikely to benefit from the mandates.
-
SEC Oversight of Private Equity and Hedge Funds
Abstract
We examine the effects of Securities and Exchange Commission (SEC) oversight on private fund advisers. We propose that SEC investigations could improve advisers’ disclosure and governance, facilitating advisers’ fundraising. However, private fund investors may view investigations as negative signals, reducing fundraising ability, or may focus on private communication with advisers or attributes other than disclosure and governance, suggesting no effect of SEC oversight on fundraising. Consistent with benefits from SEC oversight, fundraising increases for investigated advisers following SEC investigations. Consistent with our proposed mechanisms, investigated advisers’ governance over financial reporting and disclosure transparency both increase following investigations. Increases in fundraising concentrate in investigated advisers with improved disclosures. These results further concentrate in advisers that reduce their investors’ required minimum investment following investigations, suggesting that an expanding investor base also drives results. Altogether, our evidence suggests that SEC investigations of advisers improve information for investors and facilitate capital formation. Our study provides new insight for regulators as they increasingly focus on private markets and contributes to the longstanding debate over regulation in private markets, especially as they open to a broader set of investors.
-
Can Audit Industry Market Share be Bought? Evidence from Audits in the Private Equity and Hedge Fund Industry
Abstract
Understanding how auditors gain industry market share is a fundamental, but empirically underexplored, issue in accounting research. We examine one previously unexplored way that auditors can gain industry market share: the acquisition of an industry-focused competitor. We find that the number of audit clients switching to the acquiring auditor increases following the merger, above and beyond the clients directly acquired. However, this increase is more than offset by an increase in the number of clients switching from the acquiring auditor. A poor fit between the large, acquiring auditor and the acquired clients leads to the loss of small acquired clients. Further, the acquiring auditor loses more existing clients after the merger. In sum, we find little evidence that the acquisition of an industry competitor increases industry market share. More broadly, our study is one of the few that directly examines client responses to a merger involving their supplier.
- Determinants of Voluntary Audits of Internal Controls over Financial Reporting: Evidence from Private Equity Funds
-
Organizational Form Choice for Private Equity-Backed Portfolio Companies
Abstract
Private equity (PE) funds are sophisticated asset managers that focus on generating returns for investors. Despite this fact, many studies conclude that PE funds often use a tax-inefficient organizational form for their portfolio companies (e.g., startups), incurring a tax cost of about 5% of funds’ invested capital. Using a model that more fully incorporates PE fund taxation, we find the opposite result: analyzing the same data as prior research, we find that PE funds save about 8% of invested capital by using the supposedly ‘tax-inefficient’ organizational form for their portfolio companies versus the alternative organizational form. However, this tax advantage is not borne equally by investors, including fund managers who face additional taxes of about 0.1% of invested capital under the ‘tax-inefficient’ organizational form. The Tax Cuts and Jobs Act of 2017 reduces the tax differences across portfolio companies’ alternative organizational form choices. Our model informs PE fund managers evaluating organizational form choice and policymakers considering potential outcomes of tax changes. More broadly, we are the first to incorporate heterogeneous investor-level taxes into an organizational form model. We demonstrate that this innovation in our model can generate vastly different organizational form preferences than suggested by existing models.
-
Mark-to-Market (or Wealth) Taxation in the U.S.: Evidence from Options
Abstract
Recent U.S. tax proposals under various names (e.g., wealth taxes, estate tax reform, etc.) center on mark-to-market (MTM) taxation, which eliminates investors’ ability to defer or avoid capital gains taxes. To provide insight on potential effects of these tax proposals, we exploit a unique U.S. setting where “index” options on the S&P 500 Index (SPX) face MTM taxation whereas nearly identical “non-index” options on the exchange traded fund (ETF) tracking the S&P 500 Index (SPY) do not. We find new evidence of asset price consequences to MTM taxation, suggesting that MTM taxation depresses asset prices as investors appear to avoid assets subject to MTM near year-end. Additional analysis suggests this result is driven by tax, rather than administrative, costs of MTM. From a policy perspective, this suggests that 1) MTM taxation has negative, unintended market consequences in the U.S. and 2) U.S. investors will engage in actions to avoid MTM taxation. Both attributes caution policymakers in any attempts to broaden MTM taxation.
Works in Progress
- Pricing of Tax Risk in Acquisitions
- Incentivizing Charitable Contributions: Evidence from Donor Advised Funds and Private Foundations
Other Publications, Policy Commentary & Media
- Private Equity Secondary Markets
- Monitoring in Private Equity
- Private Equity Fund Pricing in Secondary Markets: Effect of Taxes and Fund Structure (reprint)
- Commentary on the SEC's Proposal to Mandate Private Fund Adviser Audits
- Commentary on the SEC's Review of the Provisions of Title IV of Dodd-Frank
- Professor: PF Audits Cost Much, Do Little
- Financial Reporting Choices of Large Private Firms
- Financial Misconduct and Strategic Corporate Disclosures
Selected Presentations
A complete list of presentations, conference participation, and service appears in the CV.
Teaching
I teach taxation and private equity at the undergraduate, master's, and executive MBA levels.
Graduate & Executive Education
Undergraduate
Mentorship & Departmental Service
I serve on the Graduate Admissions Committee (2019–present), the Research Workshop Committee (2024–present), and the Faculty Recruiting Committee, and I am host faculty for the Central Texas Tax Symposium (2018–present). I have also mentored student teams in the Deloitte FanTAXtic Case Competition (2020–2022).
Prospective students: if you are interested in empirical research on private markets, taxation, or financial reporting, please feel free to reach out by email.
Data & Code
Replication materials organized by project. Each archive contains the sample construction code, variable definitions, and the derived data that licensing permits me to share.
-
Textual Analysis of Private Equity Fund Mandatory SEC Filings: Evidence from ESG Disclosures and Fundraising Outcomes
Complete replication pipeline, run in numbered order: Form ADV Part 2 brochure preparation, FinBERT and GPT-based text measures, Preqin matching, and construction of the analysis datasets. A README documents the run order and requirements. Code only — no licensed vendor data is redistributed.